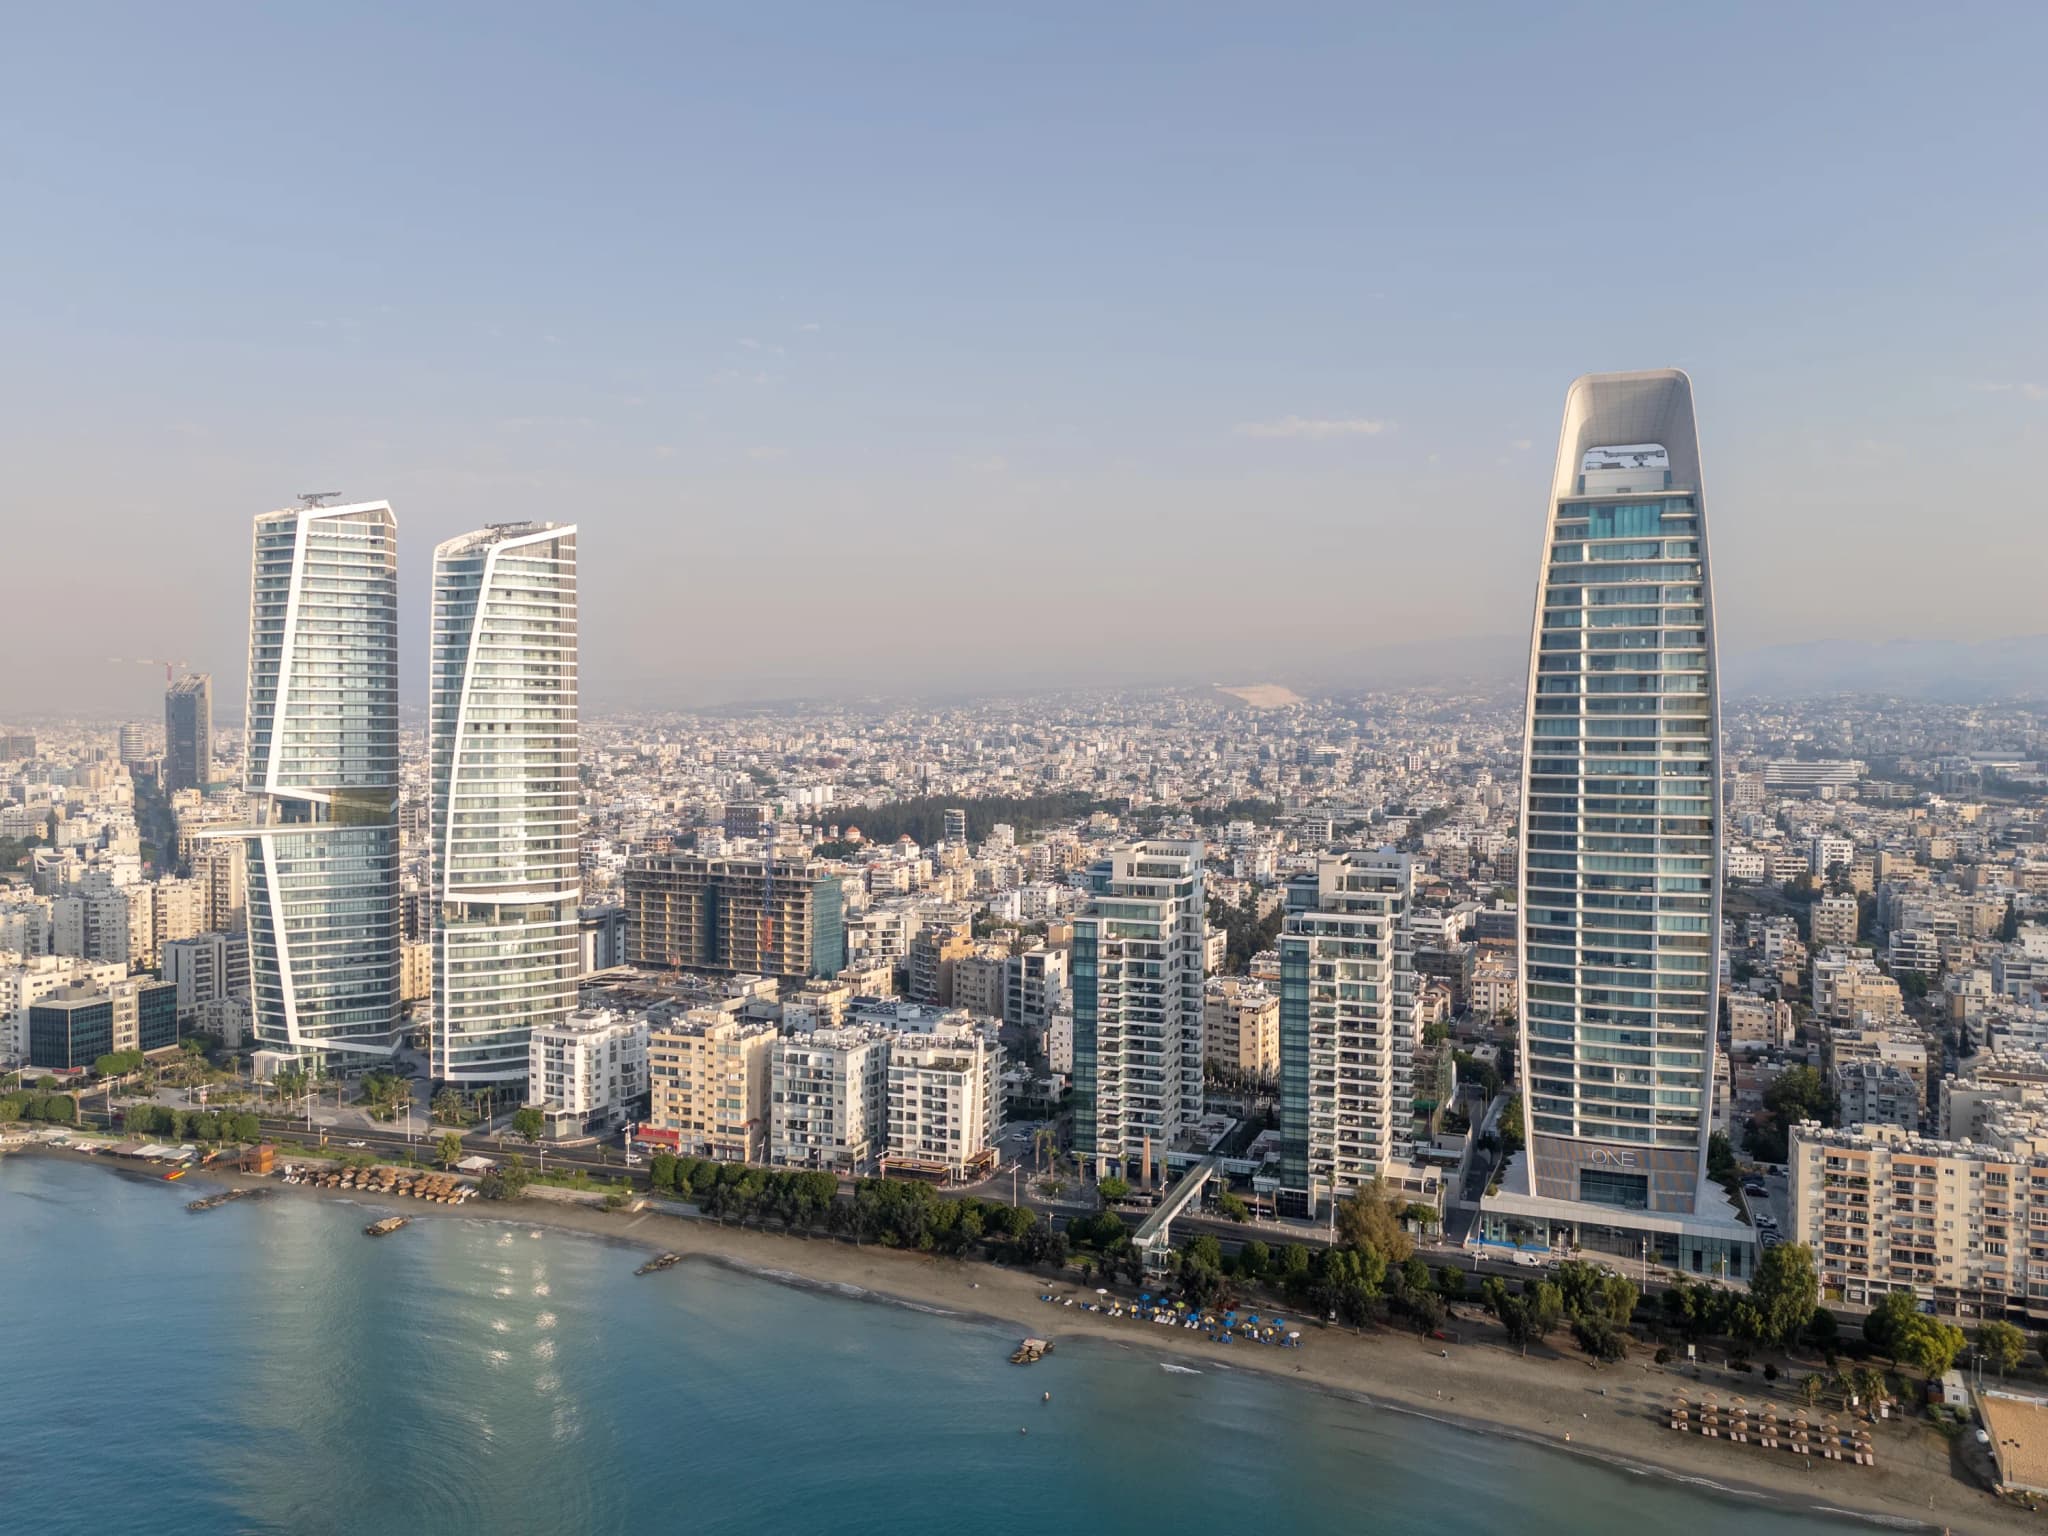

Cyprus has an appealing tax system for both residents and non-tax residents. It offers one of the lowest taxation in the EU for all resident-based companies, which is 15%.
There are also various exemptions: for example, if your annual taxable income amounts to €22,000 or less, you are exempt from personal taxation.
Read the complete guide to taxation in Cyprus, exemptions, and benefits.
Cyprus tax system
Cyprus’ taxation system obliges its tax residents to pay a specific set of taxes, including income taxation on their worldwide income, regardless of their residence status.
Foreigners who spend more than 183 days in the country usually become its tax residents: they pay taxes and receive benefits. The Government of Cyprus has simplified this rule: people who want to become tax residents of Cyprus can now stay in Cyprus for at least 60 days during the tax year instead of 183.
The 60-day rule provides for three requirements:
- Do not reside in any other country longer than 183 days.
- To carry out any activity in Cyprus, for example, to have a job in Cypriot companies.
- Own or rent residential real estate in Cyprus.
Cyprus provides its citizens and expatriates with excellent taxation policies and incentives. To be a tax resident, foreigners can have permanent residence by investing in real estate or funds.
A person who is a non-tax resident is only taxed on income arising from sources in Cyprus.
A company can be considered a tax resident if it is registered in Cyprus.
Trusted by 10,000+ investors
Check your eligibility for Cyprus permanent residence
Personal taxation
Cypriot tax residents pay an income tax on a progressive scale, file an annual return, and may be subject to various deductions.
Rates and reporting
Cyprus tax residents are subject to a progressive personal income tax on their taxable income. The tax-free threshold has increased from €19,500 to 22,000[1]Cyprus Tax Department — individual income tax rates from 2026. Current personal income tax rates are:
- up to €22,000 — 0%;
- €22,001—32,000 — 20%;
- €32,001—42,000 — 25%;
- €42,001—72,000 — 30%;
- over €72,000 — 35%.
Cyprus tax residents aged 25 to 70 must file an annual income tax return regardless of their income, including if they have no income. Residents under 25 or over 70 must file if they receive any gross income covered by the Income Tax Law, such as salary, business income, pensions, rent, dividends or interest.
Deductions
In 2026, the Cyprus tax reform introduced additional deductions for families and housing expenses. Subject to the applicable conditions and income limits, deductions for dependent children amount to €1,000 for the first child, €1,250 for the second, and €1,500 for the third and each additional child. The deduction is doubled for qualifying single-parent families.
Taxpayers may also qualify for deductions of up to €2,000 for rent or interest on a serviced housing loan for their main residence, and up to €1,000 for qualifying energy-efficiency expenditure or the purchase of an electric vehicle. A separate deduction of up to €500 is available for home insurance against natural disasters.
Taxes on corporate income
Cyprus tax-resident companies are taxed on income arising in Cyprus and abroad. From January 1st, 2026, the standard corporate income tax rate increased from 12.5 to 15%.
Non-Cyprus tax-resident companies are not automatically exempt from corporate income tax: the 15% rate also applies to profits attributable to permanent establishments in Cyprus under the Income Tax Law[2]Cyprus Tax Department — Corporate tax rates.
The previous special insurance premium tax applicable to life insurance companies was abolished as part of the 2026 tax reform.
Shipping companies are exempt from all taxation under the tonnage tax regime, provided by the Cyprus Merchant Shipping Legislation.
Don’t know where to start?
Download our one-page pathways navigator to compare the options and pick the best one
Value-added tax rates
The value-added tax, or VAT, is charged on the supply of services and goods in Cyprus, the importation of goods into Cyprus, and the acquisition of goods from the EU. The standard VAT rate is 19%.
Cyprus also has a 9% reduced VAT rate on a restaurant, catering services, accommodation, hospitality, and other services.
A 5% reduced VAT rate applies to the renovation and repair of a property.
Property taxes in Cyprus
Property owners and sellers generally pay VAT or transfer fee and capital gains tax. After the 2026 reform, the stamp duty no longer applies.
Stamp duty
Cyprus abolished the Stamp Duty Laws with effect from January 1st, 2026. Documents, contracts and agreements drawn up and signed from that date are therefore no longer subject to stamp duty. Documents signed by at least one contracting party by December 31st, 2025 remain subject to the previous stamp-duty rules.
VAT and property transfer fee
Property transfer fees depend on whether VAT applies to the purchase. VAT generally applies when buying a new property from a developer, while resale properties on the secondary market are generally not subject to VAT.
The standard VAT is 19%. It may be reduced to 5% if the property is the owner’s main place of residence.
If VAT is charged on a property purchase, no property transfer fee is payable. If VAT does not apply, as is generally the case with resale properties, transfer fees are calculated progressively:
- 3% on the first €85,000;
- 5% on the portion from €85,001 to 170,000;
- and 8% on the amount above €170,000.
The resulting transfer fee is then generally reduced by 50%. This reduction applies to transactions where transfer fees are payable under the standard property transfer rules, subject to limited statutory exceptions.
Capital gains tax
Capital gains are charged at a 20% rate. In certain cases, exemptions are applied:
- general exemption on gains from disposal of property — up to €30,000;
- agricultural land disposed of by a qualifying farmer — up to €50,000;
- disposal of a qualifying main residence — up to €150,000.
A 20% capital gains tax, or CGT, is charged on income from selling immovable properties in Cyprus or shares of companies that directly own real estate objects in Cyprus. This tax only applies to profit from selling an immovable property when the disposal is not subject to income tax.
Special contribution to the defence
The Special Defence Contribution, or SDC, applies mainly to investment income. For individuals, this mainly includes dividends from shares and interest from savings or investments.
Cyprus charges SDC only when an individual is both a Cyprus tax resident and domiciled in Cyprus. Cyprus tax residents with non-dom status do not pay SDC on dividends or interest.
Dividends distributed from profits are subject to SDC at 5%. Interest income is generally subject to SDC at 17%, but some types of interest receive more favourable treatment.
Individuals whose total annual income, including interest, does not exceed €12,000 can claim a refund so that they effectively pay SDC at 3% on their interest. A 3% rate also applies to interest from certain Cyprus or EU government bonds and listed corporate or local-authority securities.
Cyprus does not charge SDC on interest paid as compensation for disability, serious bodily injury or death.
Rental income does not fall under SDC. Companies also do not apply the deemed dividend distribution rules to profits earned from 2026 onwards.
Tax calendar
You can check a tax calendar to pay all taxes on time, be up-to-date, and avoid paying unnecessary penalties.
Tax due dates for individuals and companies are the following:
- end of each month — employers submit the monthly PAYE return and pay income tax and GHS contributions withheld from employees for the previous month. Employers also pay their own GHS contribution;
- end of each month — employers pay Social Insurance contributions for the previous month;
- end of each month — pay SDC and GHS withheld on dividends or interest paid to individuals in the previous month, where applicable;
- end of each month — pay tax withheld on certain payments made to non-Cyprus tax residents in the previous month;
- 10th day of the following month — submit the monthly Intrastat declaration, where required;
- 15th day of the following month — submit the VIES statement for qualifying intra-EU supplies of goods and services;
- 10th day of the second month after the VAT period ends — submit the VAT return and pay any VAT due. VAT periods generally cover three months;
- June 30th — pay SDC on dividends and interest received from abroad during the first half of the year if Cyprus did not withhold it at source. Pay the corresponding GHS contributions where applicable. Property owners also pay GHS on rental income for the first half of the year if the tenant did not withhold it;
- July 31st — pay the first instalment of provisional income tax for the current tax year. This mainly applies to companies and self-employed individuals who expect to have taxable income;
- December 31st — pay the second instalment of provisional income tax. Taxpayers can also revise their provisional tax estimate by this date;
- December 31st — pay SDC on foreign dividends and interest for the second half of the year where Cyprus did not withhold it at source, together with applicable GHS contributions. Pay GHS on rental income where applicable. Rental income itself is not subject to SDC from 2026;
- March 31st of the following year — employers submit their annual PAYE return covering salaries and tax and contributions withheld during the previous tax year;
- July 31st of the following year — individuals generally submit their annual income tax return. From the 2026 tax year, returns are submitted through Tax For All. The government may extend this deadline for a particular year;
- January 31st of the second year following the tax year — companies and self-employed individuals who prepare audited or reviewed financial statements submit their income tax return. For example, the return for tax year 2026 is due on January 31st, 2028.
Most taxes are paid though the Tax For All system. Social contributions are paid through the Social Insurance Services portal.
Tax exemptions for non-Cyprus residents
Cyprus’ taxation system offers numerous exemptions and benefits for non-residents on capital gains, employment income, VAT exemptions, and many others.
For example, non-Cyprus residents are exempt from tax on interest and dividends in the whole amount. Non-residents are also exempt from income taxes on the sale of securities and capital sums accrued to individuals due to any payments to approved funds.
Trusted by 10,000+ investors
Sort out your tax obligations before it becomes a problem
Valid double taxation treaties
The Ministry of Finance of Cyprus lists double tax treaties with 72 countries in total, but agreements with Curaçao, Hong Kong and Viet Nam have been signed and have not yet entered into force.[3]Cyprus Ministry of Finance — Double Tax Treaties
Most of the countries on the list follow the OECD Model Convention, but a tax treaty with the United States is also adapted to the US Agreements.
Complete list of countries that have signed double taxation with Cyprus
How to obtain permanent residence in Cyprus by investment to become a tax-resident
The Cyprus tax policy is softer than in many countries, so numerous business owners and individuals choose this country as their residence. Participating in the investment programme is the fastest way to get Cyprus permanent residence.
The Government of Cyprus has launched a programme that allows foreigners to get permanent residence by investment. The minimum investment amount is €300,000. Applicants must also demonstrate a secure annual income of at least €50,000, increased by €15,000 for a spouse and €10,000 for each dependent minor child.
You can invest in residential property, commercial real estate, local investment fund units, or Cypriot companies shares. Eight years after receiving residence, you can apply for citizenship.
Buying a residential property. Foreigners can buy one or two properties for €300,000+ in new buildings. They also have to pay a value-added tax of 19%; if housing is purchased for their own usage, the VAT is 5%.
Investing in commercial real estate. Foreigners can buy one or two commercial properties for €300,000+ in new buildings or the secondary market.
Buying units of local funds for at least €300,000 and only from collective investment funds of the RAIF, AIF, and AIF LNP types.
Purchasing shares of Cypriot companies for €300,000 and more, which have five employees and make a profit on the island.
Examples of properties to buy to obtain residence by investment
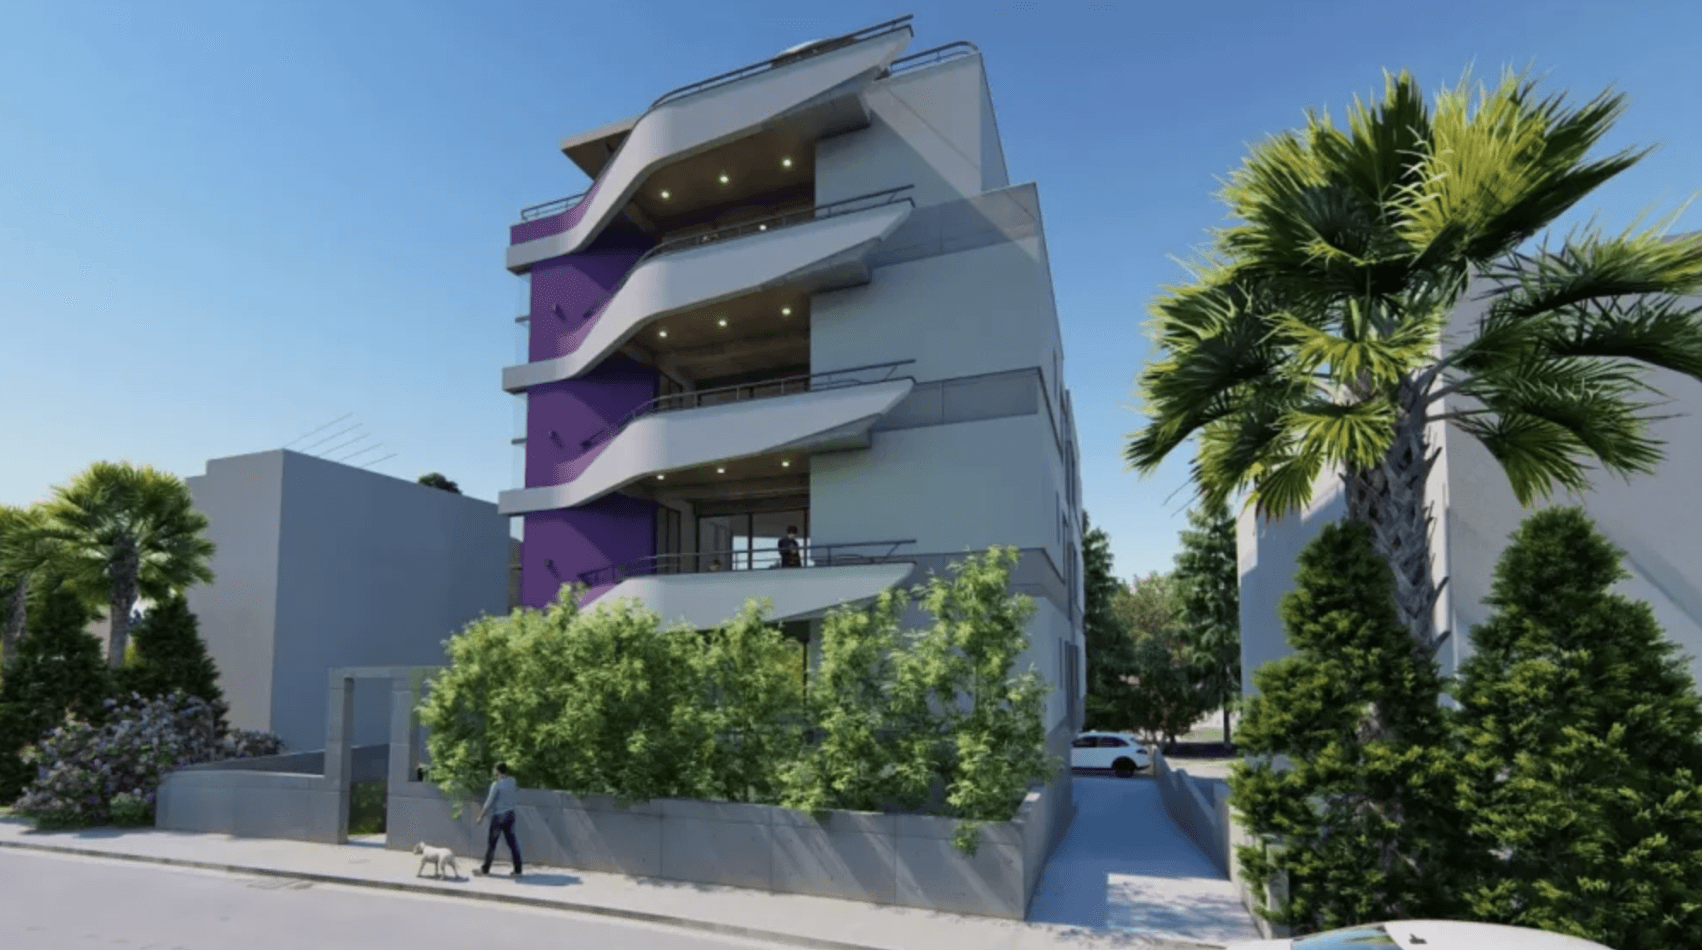

Cyprus, Limassol
€1,300,000 — €2,200,000
Modern apartments with bright elements, Agios Athanasios, Limassol
 96 m² — 585 m²
 1—6
 1—6
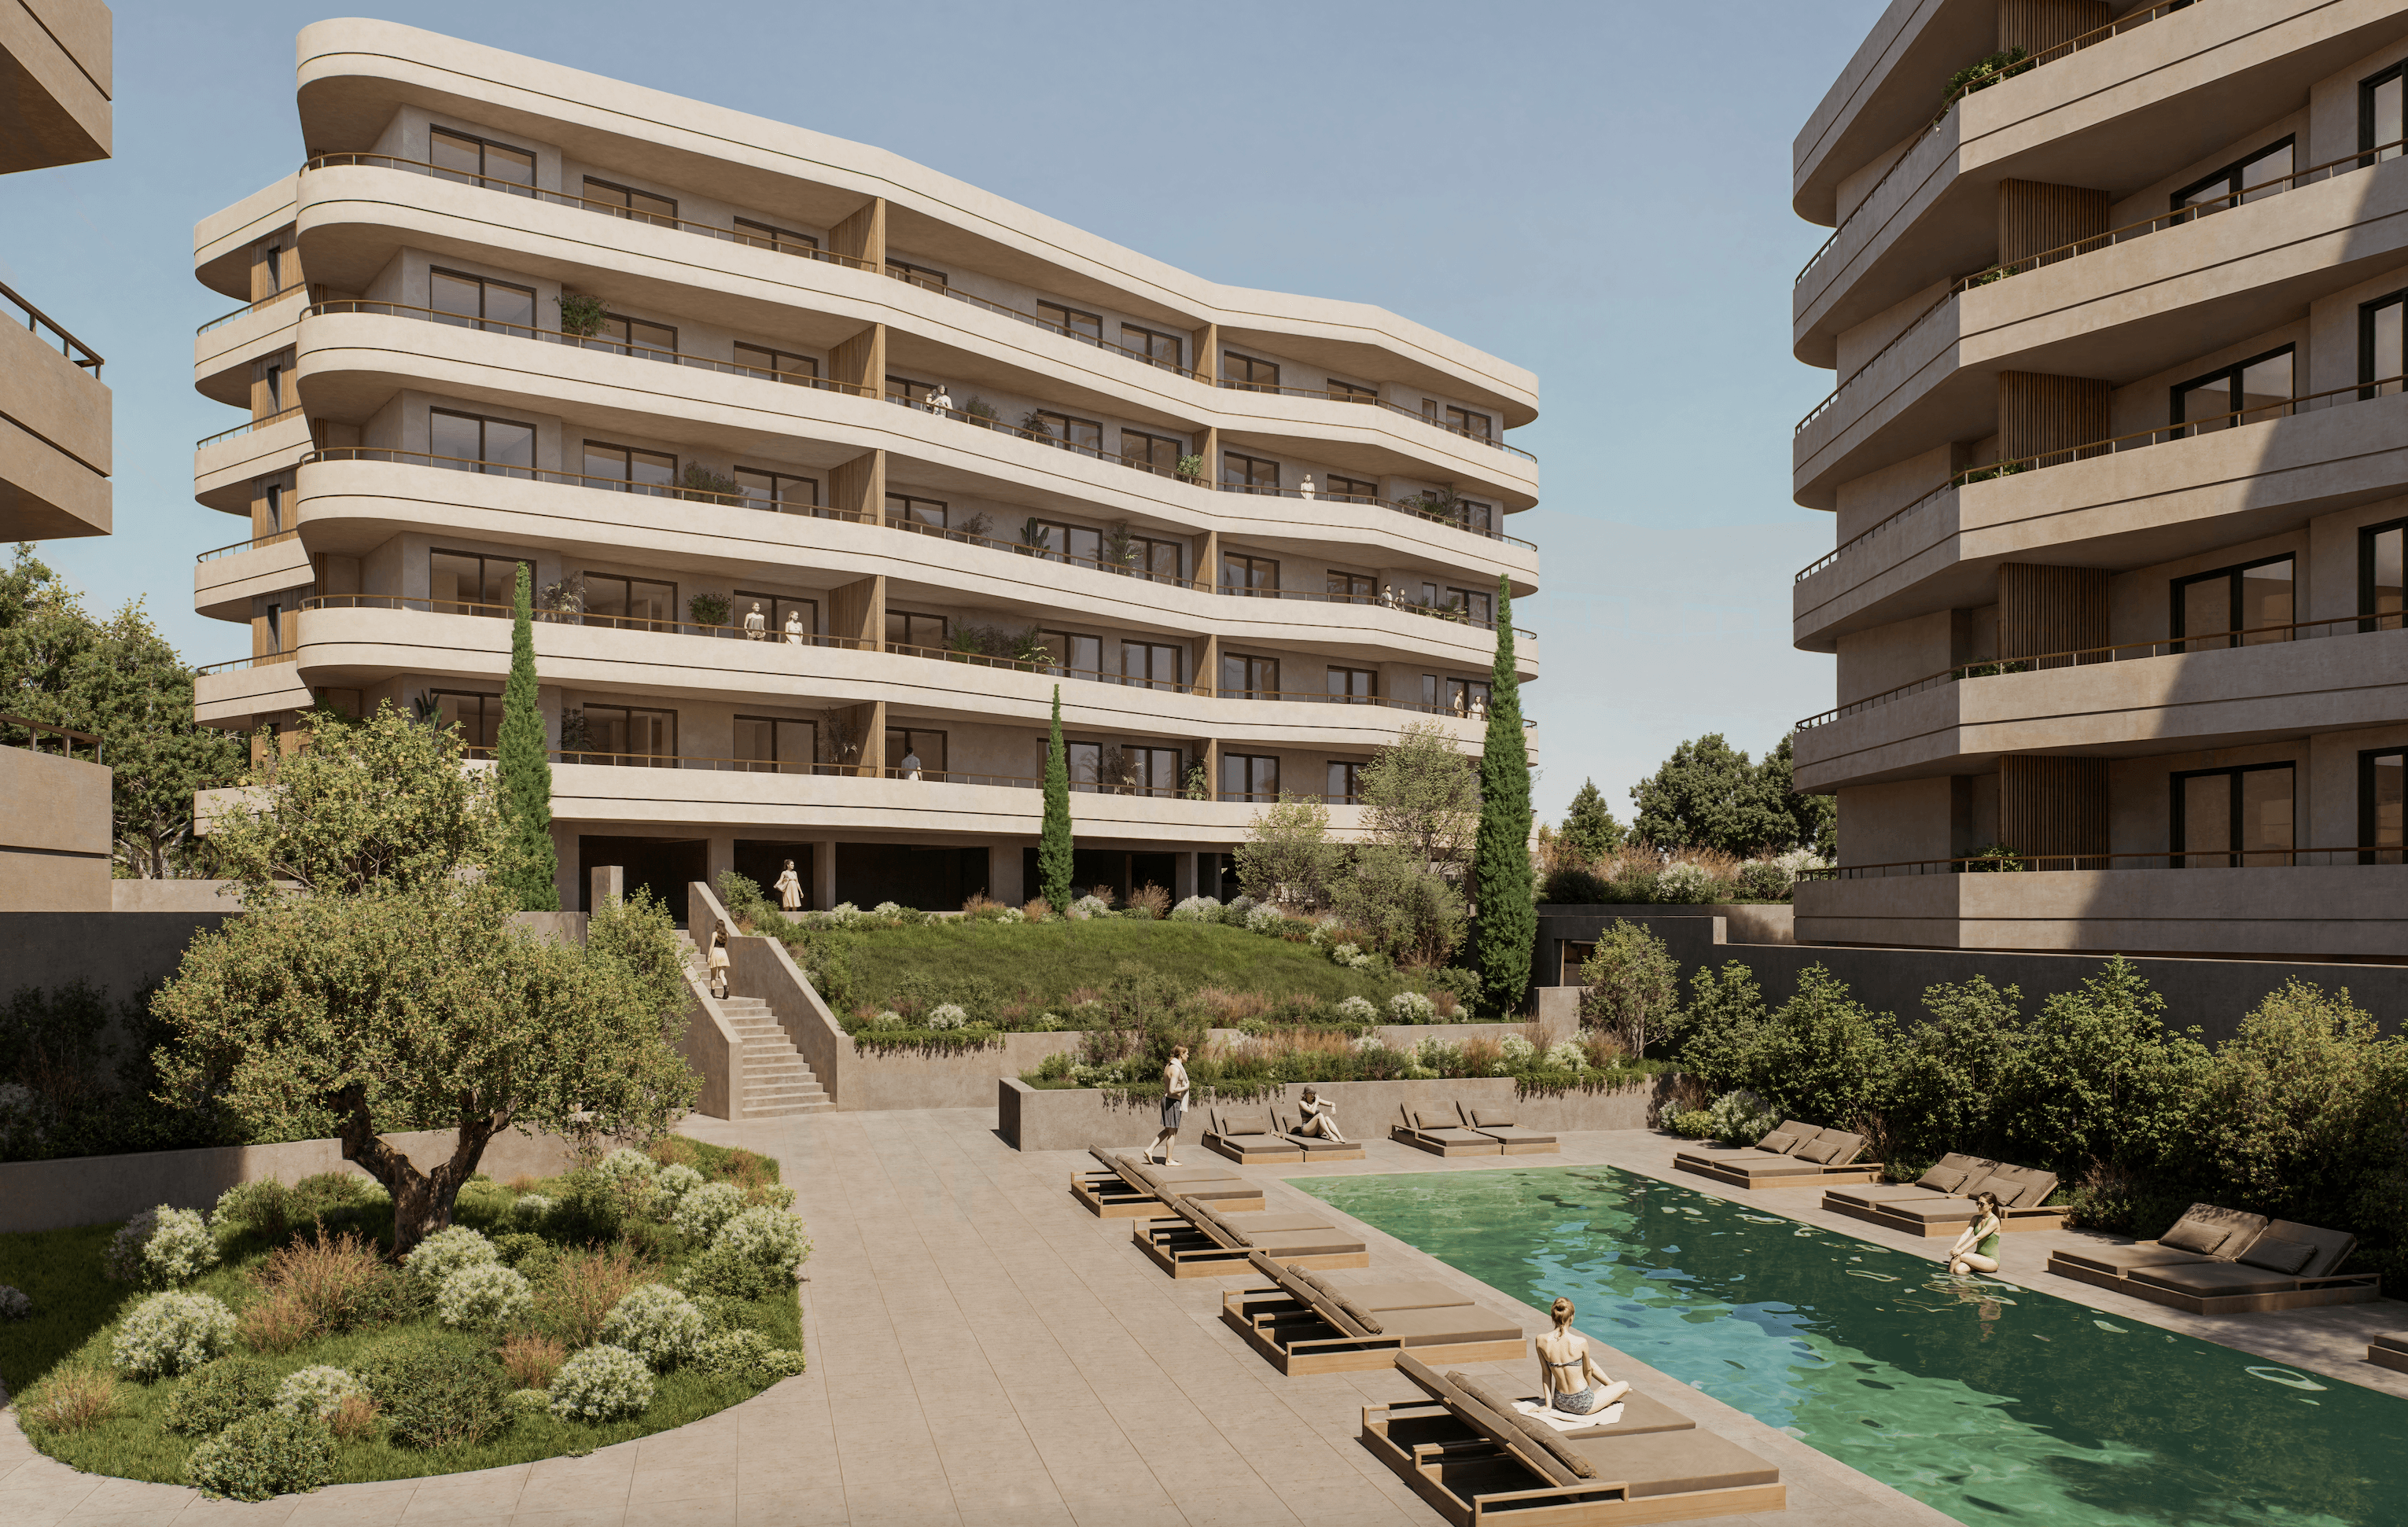
Cyprus, Limassol
€179,000 — €508,000
Elegant and stylish apartments, Germasogeia, Limassol
49 m² — 145 m²1—4 1—4 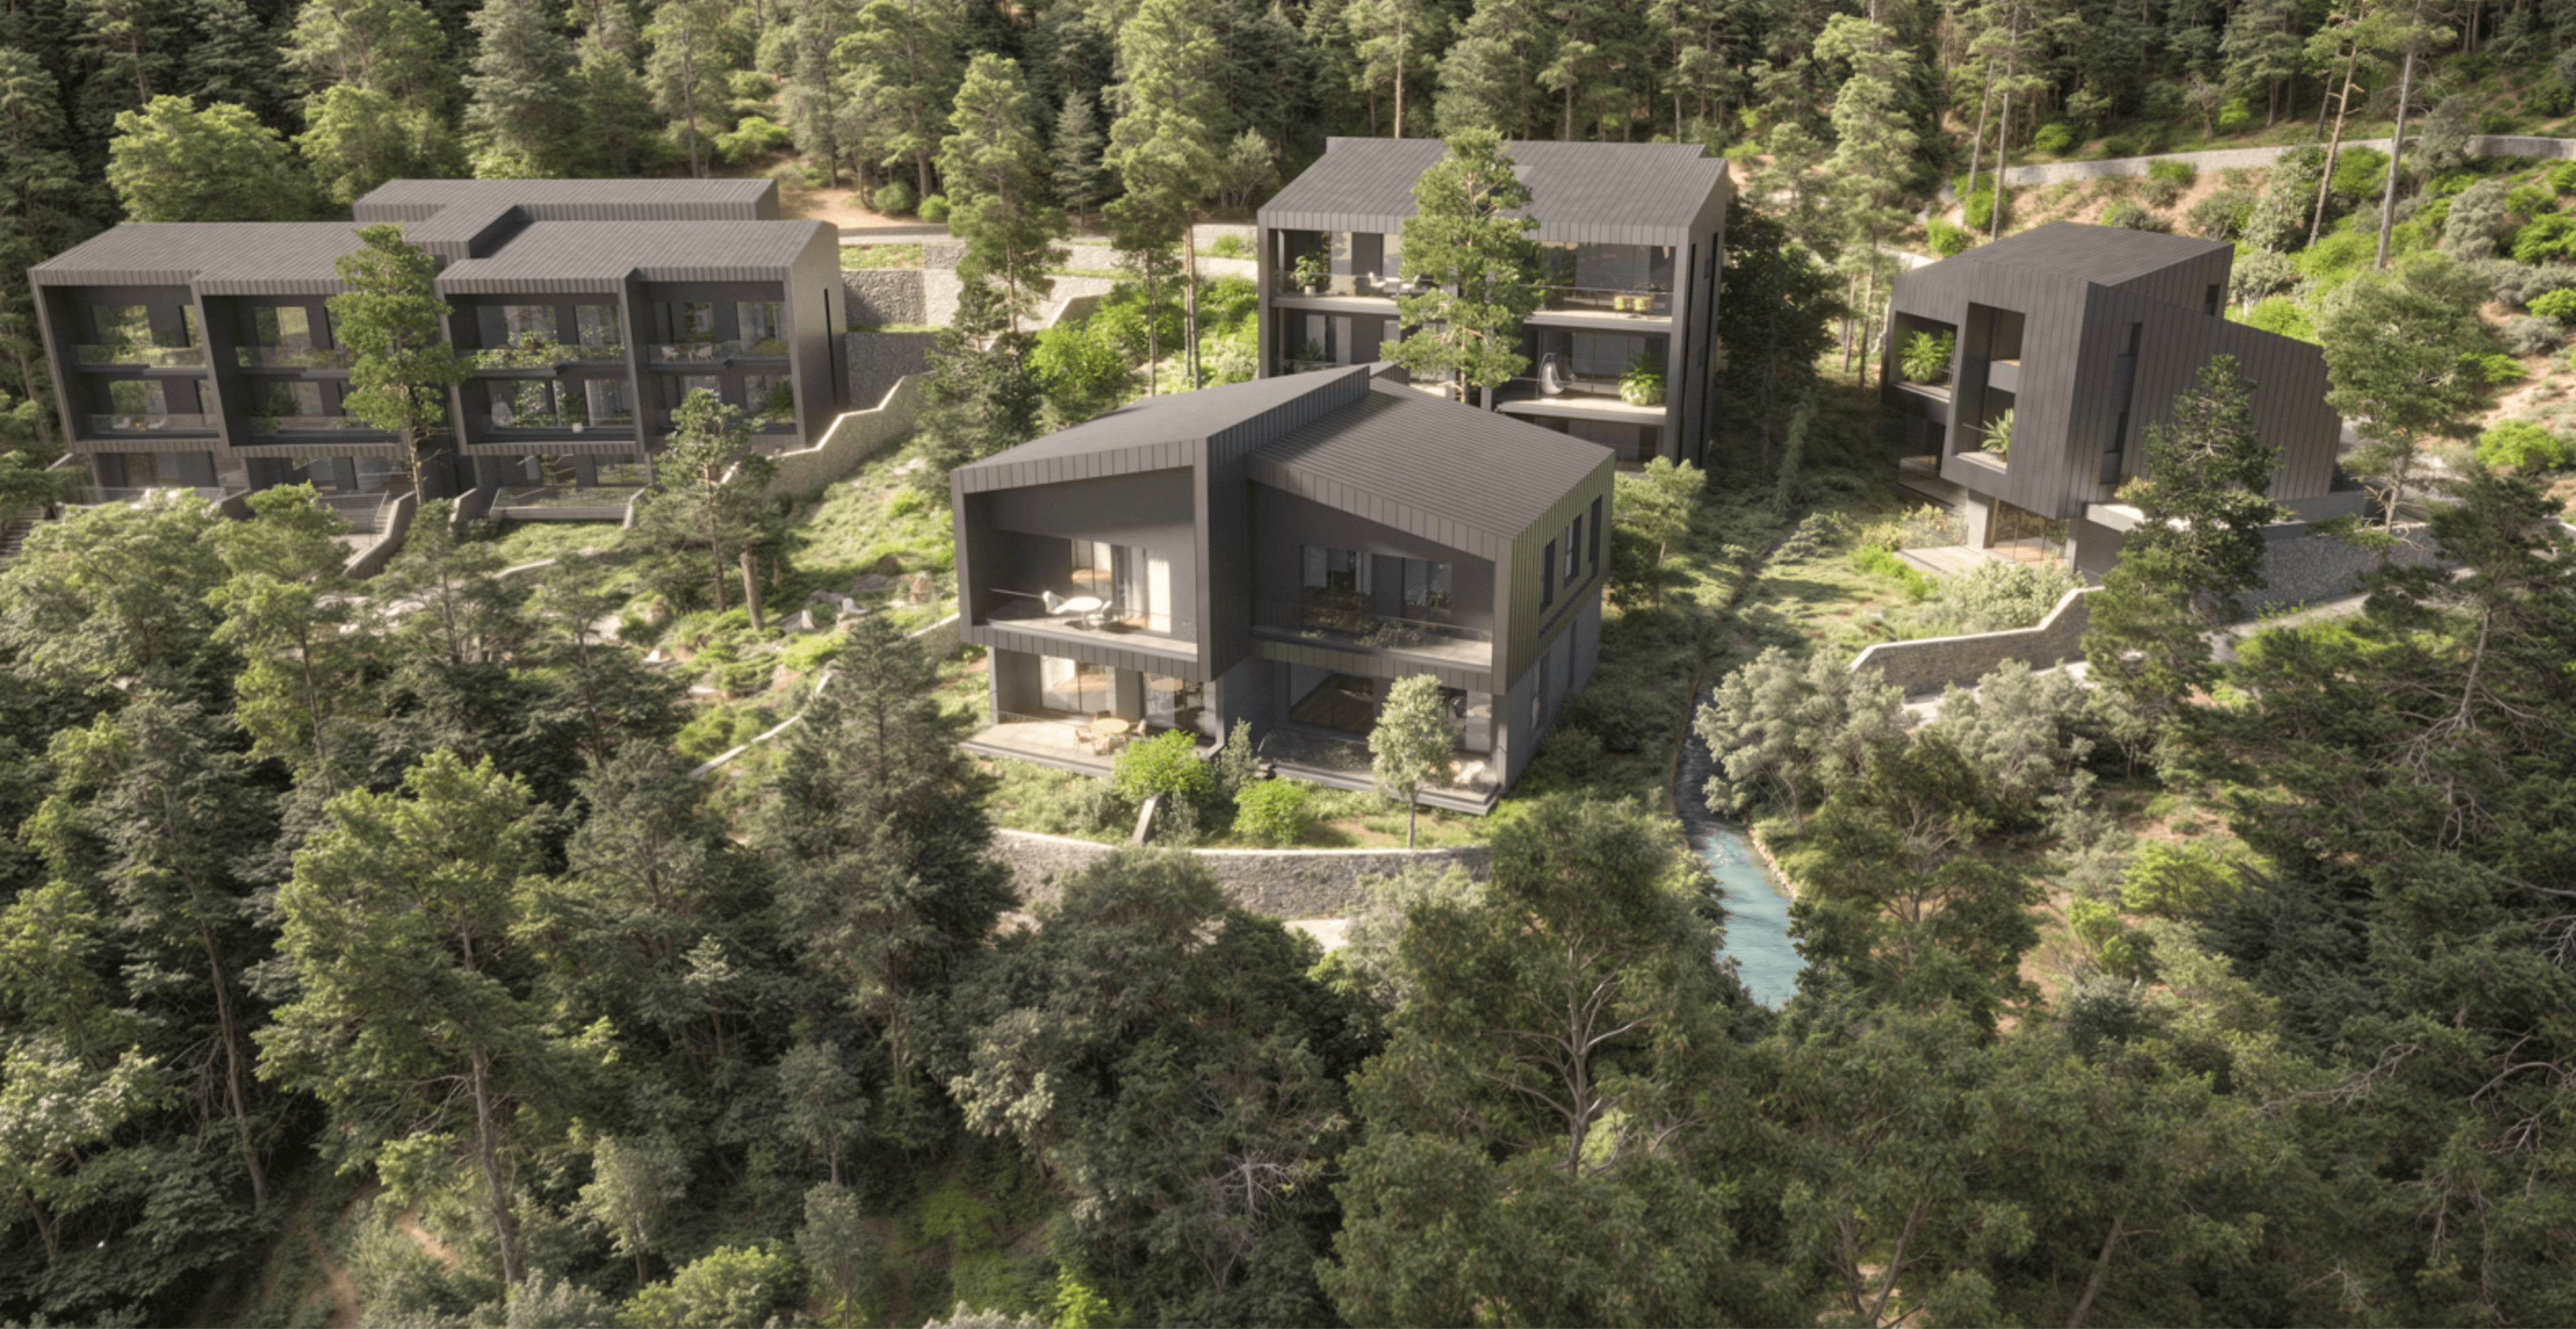
Cyprus, Trodos
€530,000 — €1,300,000
Stylish apartments and houses with pine forest view, Prodromos, Trodos
97 m² — 205 m²1—3 1—3 Key takeaways on taxes in Cyprus
- Cyprus tax residents generally pay tax on worldwide income, while non-residents are taxed mainly on Cyprus-source income. A person may qualify as a tax resident under either the 183-day or 60-day rule.
- Personal income tax ranges from 0 to 35%. The first €22,000 of taxable income is taxed at 0%, while the 35% rate applies above €72,000.
- The standard corporate income tax rate is 15%. Cyprus tax-resident companies generally pay tax on income earned both in Cyprus and abroad.
- Cyprus non-dom tax residents do not pay the Special Defence Contribution on dividends or interest. For domiciled tax residents, dividends are generally subject to 5% SDC and interest to 17%, with some reduced rates and exemptions.
- Foreign investors can obtain Cyprus permanent residence with an investment of €300,000+ in qualifying property, funds or Cypriot companies; tax residence depends separately on meeting Cyprus tax-residence rules.
Immigrant Invest is a licensed agent for citizenship and residence by investment programs in the EU, the Caribbean, Asia, and the Middle East. Take advantage of our global 15-year expertise — schedule a meeting with our investment programs experts.
 Trusted by 10,000+ investors